For Emily, the best financial tools fit the life she’s already planned
The 35-year-old Orlando-based project manager knows how she likes to manage her money. Cash App and Afterpay give her different ways to keep it moving, plan purchases around her income, and leave room for both the essentials she needs and the activities she enjoys.
Emily knows what she likes, and she knows how to make the things she already enjoys work a little harder for her budget. That mindset shows up in her everyday choices, like her regular coffee order, where Cash App¹ has become essential to that routine.
“I am an avid Starbucks drinker,” Emily said. “[Cash App will] do 5% or 3% cash back on Starbucks, so I really use Cash App to take advantage of [their Offers].”
It’s a small example of the way Emily thinks about money more broadly: if she’s already buying the coffee, why not make financial tools work for her needs?
When a bigger purchase comes along, planned or otherwise, Emily applies the same thinking. She knows what she can comfortably spend, understands her options, and chooses the best tool that fits the plan. Together, Cash App and Afterpay² give her different ways to put that approach into practice.
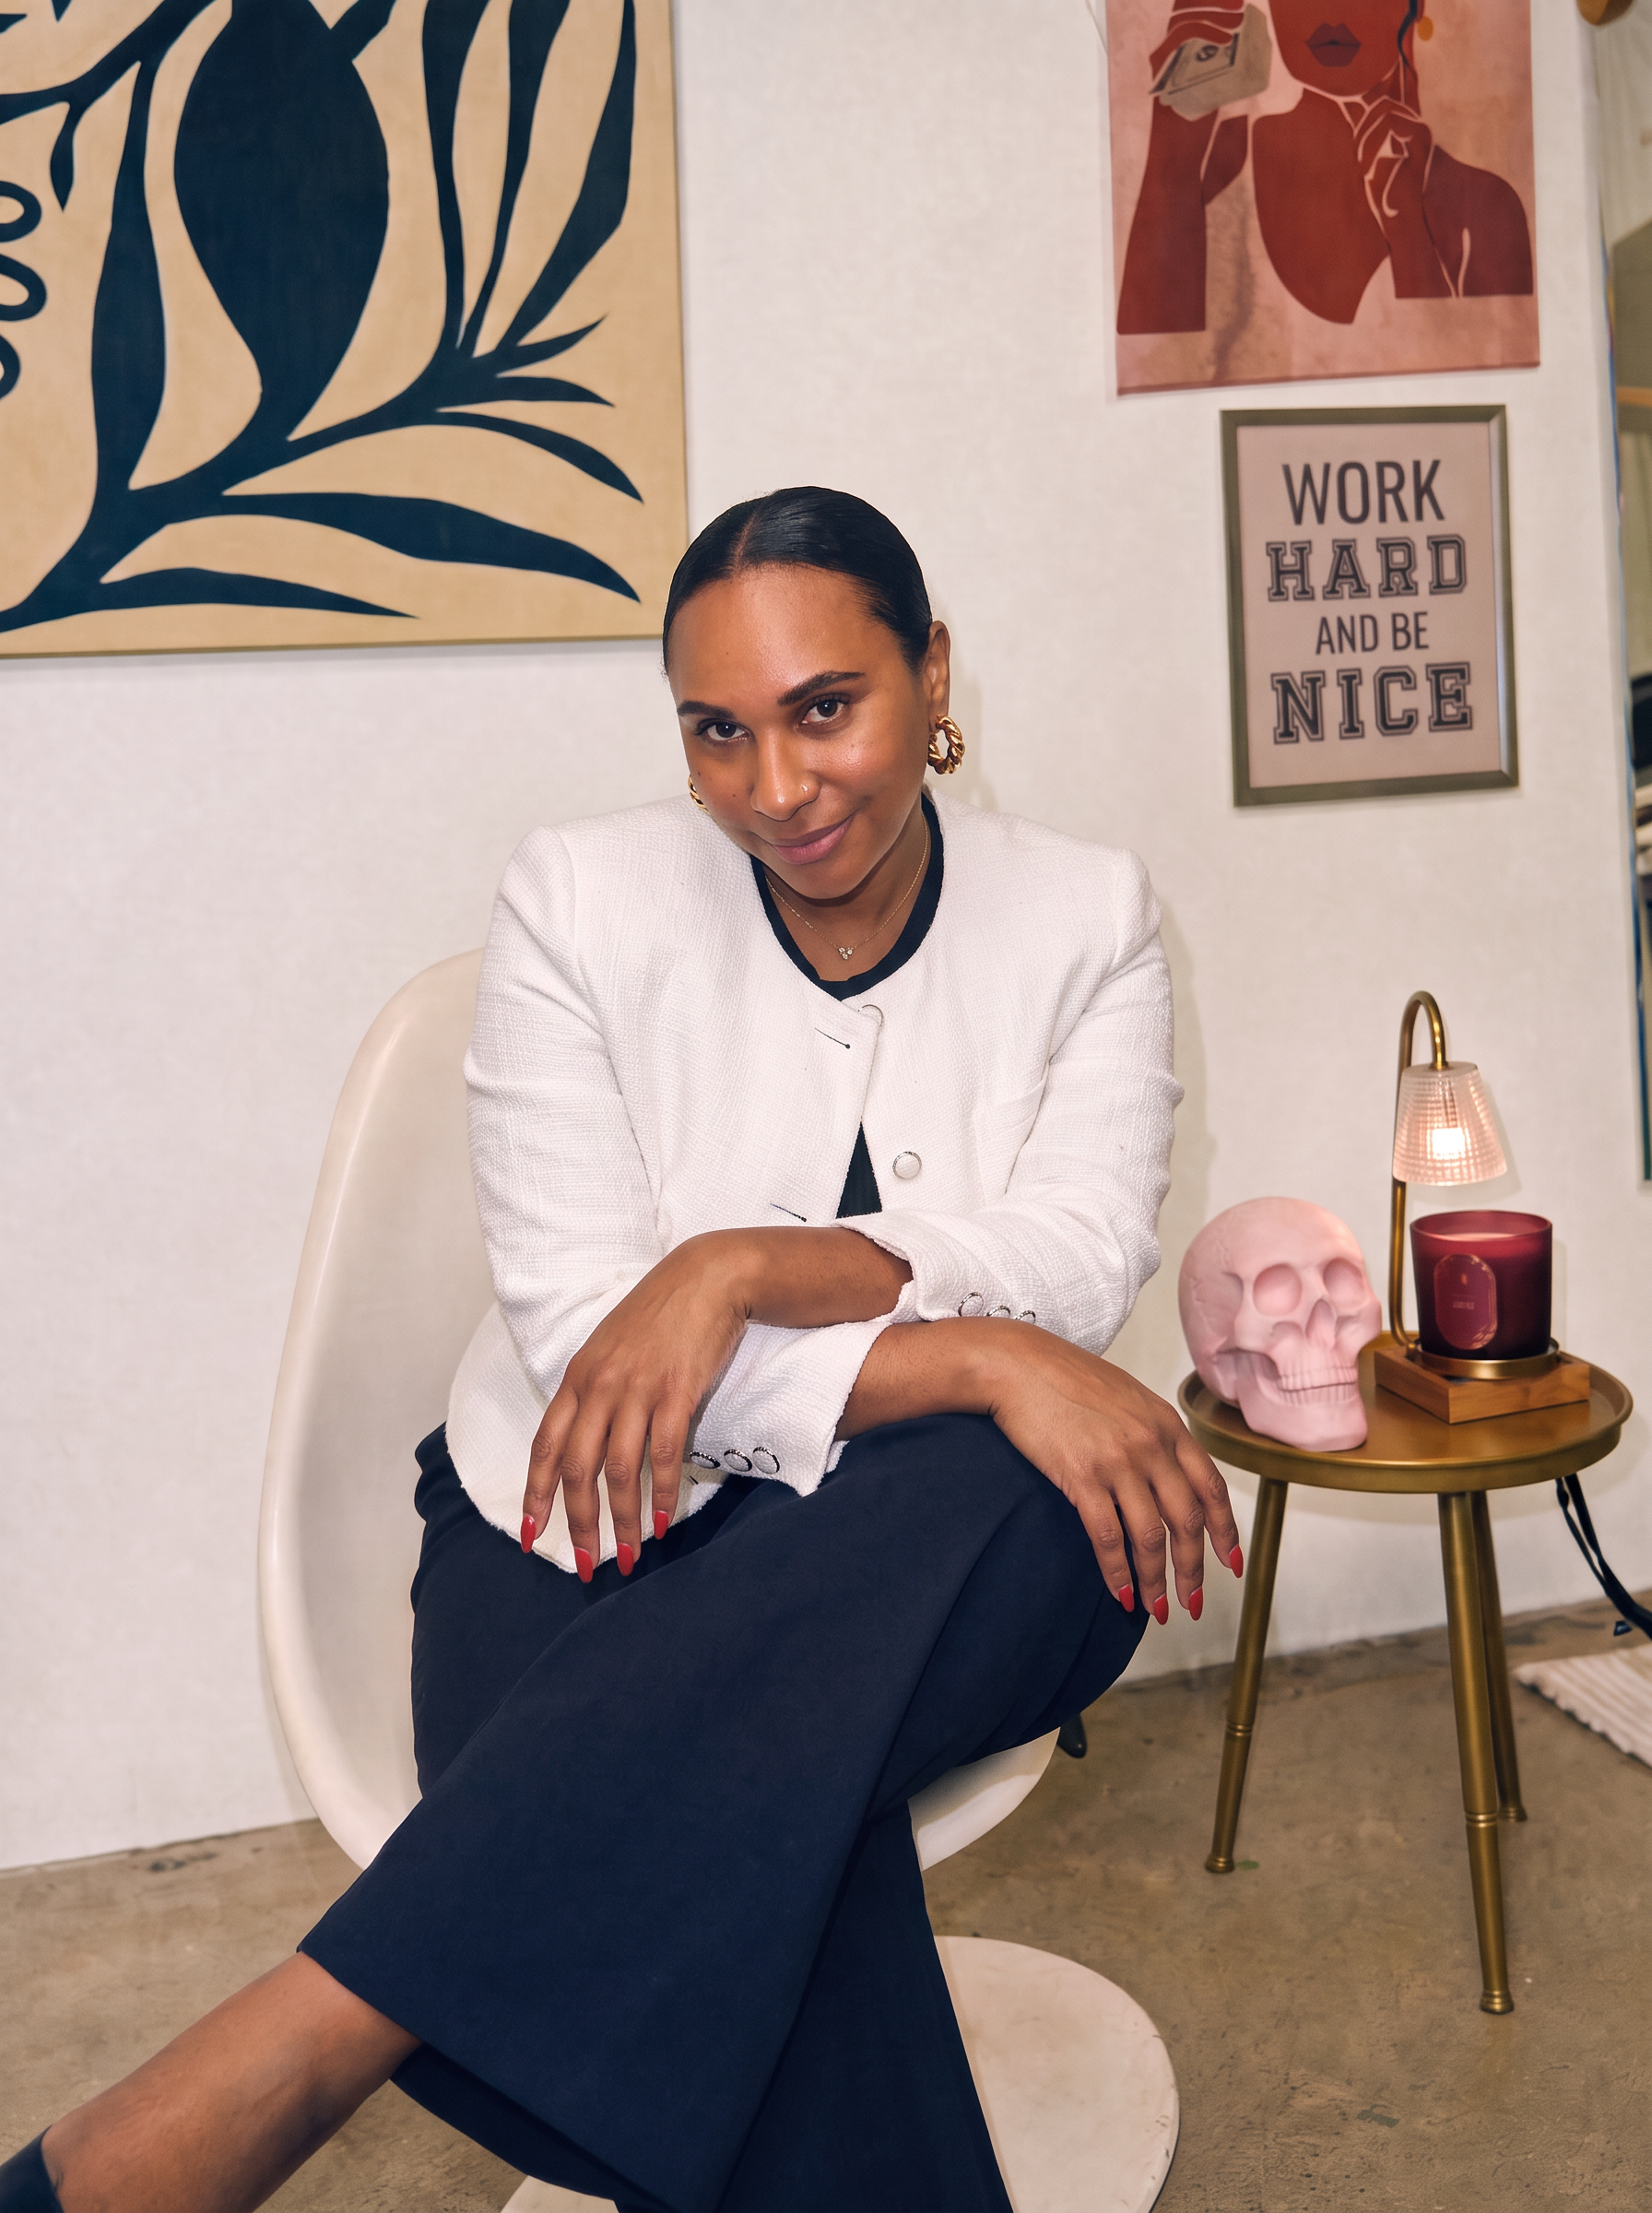
Based in Orlando, Emily Pherigo uses Cash App and Afterpay to manage her budget and daily expenses.
A recommendation worth passing along
Before she discovered Afterpay, Emily’s first experience with using a pay-over-time product was to buy herself a new couch. The couch stayed, but her enthusiasm for the payment experience didn't.
“I just wasn't super thrilled with the payment terms,” Emily said. “I felt like it wasn't tailored to my work and payment schedule.”
Then, her friend suggested she try Afterpay.
Emily started with a smaller purchase. She found the app experience easier to use, liked getting notifications that helped her keep track of upcoming payments, and found she could use Afterpay across more of the places she actually wanted to shop.
That range matters to Emily.
“You have the mom and pops and then you have Saks Fifth Avenue,” she said.
Now, rather than stretching her budget for a purchase, Emily makes sure her Afterpay payments fit within the plan she already has.
“I always try to make sure that I use it when it aligns with my pay schedule,” she said.
Making the numbers work for her
For Emily, financial planning starts with her budget: what she can pay today isn’t necessarily what she can afford overall. The tools she uses have to work within that budget, not change it.
When Emily used Afterpay to purchase one of their offered Gift Cards for groceries, for example, she started with the $150 she had already budgeted for the month. Splitting that $150 into four no-interest payments over time gave her flexibility in when she paid, without changing how much she planned to spend overall.
“I tried to be realistic in costs,” she said. “This is how much I would spend a month on groceries, so this is how much you're going to spend on Afterpay. So that way there were no surprises later on in the month.”
It's how Emily creates room for choice without losing sight of everything else her money needs to do - like bracing for unexpected expenses.
When the budget takes a detour
Of course, not every expense makes it onto the budget ahead of time. When Emily unexpectedly needed to replace all four tires on her car, she approached it the same way she would any other purchase: look at what she had coming up, consider her options, and figure out what worked within her budget.
That included checking Afterpay to see whether an automotive retailer like AutoZone was available. For Emily, it was another example of why she values having financial tools that can flex across different parts of her life (from the purchases she plans for to the ones that show up unexpectedly).
It’s also the kind of knowledge Emily and her friends share with one another. A friend first introduced her to Afterpay after hearing about her experience with another pay-over-time service. Since then, Emily has found herself on the other side of the conversation, recommending Afterpay to friends looking for more flexibility with everyday expenses.
Financial advice, in Emily's circle, goes both ways.
Money that moves with her
These days, Emily is working as a project manager, and when it comes to her everyday money (or her next coffee), Cash App is the money app she reaches for.
Part of that is practical. Her sister doesn't have a traditional bank account, so Cash App gives them a way to send money back and forth.
But she also likes not having to think too hard about how she'll pay when she's out.
“I don't need to carry a traditional wallet with me. It's just been nice to be able to just rely on that.”
That convenience connects back to what initially drew her to the platform: using financial tools that fit into the life she's already living.
Cash App helps her keep everyday money moving. Afterpay gives her another way to plan certain purchases around her budget and income.
The products do different jobs, but Emily approaches both the same way: she knows what she wants her money to do first, then chooses the tools that help her do it.
The luxury bag can wait
Emily’s advice for first-time Afterpay users is simple.
“You don't have to buy a Chanel bag,” she said with a laugh. “You can start off small…Be reasonable in attaining what you want and need,” Emily said.
It’s an approach that leaves room for all of it: her coffee, money sent to her sister, the things she wants, and the expenses she didn’t see coming. And when she finds something that works for her, chances are her friends will hear about it, too.
And if four tires decide to interrupt the plan? She'll look at the options and do the math.
- Cash App is a financial services platform, not a bank. Banking services provided by Cash App's bank partner(s). Prepaid debit cards issued by Sutton Bank, Member FDIC. Cash App Visa® Debit Flex Cards issued by Sutton Bank, Member FDIC, and The Bancorp Bank, N.A., pursuant to a license from Visa U.S.A. Inc. See terms and conditions for the Sutton prepaid card at cash.app/legal/us/en-us/card-agreement, for the Sutton debit flex card at cash.app/legal/us/en-us/debit-flex-card-agreement-sutton and for the Bancorp debit flex card at cash.app/legal/us/en-us/debit-flex-card-agreement-bancorp. Offers provided by Cash App, a Block, Inc. brand. Offers may not be affiliated with third party merchants.
- Afterpay is offered and managed through your Cash App account - no Afterpay account needed. Eligibility is based on several factors and is not guaranteed. Afterpay is not available in all states. Afterpay loans issued by First Electronic Bank, serviced by Square Capital, Inc. View state licenses at sqcapitallicenses.com/us/en/legal/capital/capital-licenses